Tag Archive for: Climate targets

EU ETS Maritime: Obligations and options for action for maritime transport (Part 1)

Since 2005, the EU Emissions Trading System (EU ETS) has been the European Union’s (EU) central market-based climate instrument. Since 2018, the maritime transport sector has been required to measure, report and verify emissions in accordance with EU ETS rules (monitoring, reporting, verification – MRV), and emissions pricing began on 1 January 2024. In this first part of a series on the EU ETS for maritime transport, the basics of the obligations for affected companies are explained.

This extension of the EU ETS to maritime transport was part of the ‘Fit for 55’ package and covers all ships with a gross tonnage (GT) of 5,000 or more that call at ports in the EU or the European Economic Area (EEA), regardless of their flag. Shipping companies were therefore assigned to national administrative authorities on 30 January 2024 (source: EU). This assignment list is not exhaustive, as companies may still be subject to regulation after the deadline and are obliged to comply despite not being listed. The shipping sector already contributed around 6% of EU ETS emissions in its introductory year 2024 (source: EEA) and caused around 13% of all transport-related greenhouse gases in the EU in 2021 (source: EMSA).

The first evaluation of the integration of shipping into the EU ETS by the EU Commission in March 2025 shows that over 5,000 shipping companies are registered on the European MRV platform THETIS-MRV and that verified monitoring plans for more than 15,000 ships are available (source: EU Commission). Figure 1 illustrates the geographical scope of the EU ETS for maritime transport: 100% of emissions for intra-EU/EEA voyages are covered, while 50% of emissions are subject to taxation for voyages to/from third countries. This regulation aims to prevent carbon leakage and minimise avoidance behaviour.


Scope of EU ETS Maritime

Figure 1: Example illustration of the scope of the EU ETS maritime with the 100/50% rule (source: carboneer)

Gradual inclusion of shipping

The EU ETS operates on a cap-and-trade principle with an annually decreasing emissions cap. Shipping companies must purchase corresponding emission allowances (European Union Allowances (EUA)) for each tonne of CO₂ equivalent emitted and surrender them in the Union Registry each year. Companies with low CO₂ abatement costs can sell their EUAs to companies with high abatement costs. This means that CO₂ is avoided where it is most efficient and cost-effective.

The inclusion of shipping in the EU ETS is taking place in stages. While only CO₂ emissions are subject to pricing for the time being, methane and nitrous oxide will also be priced from 2026. From 2027, the system will also cover offshore vessels with a GT of over 5000. While smaller ships between 400 and 5,000 GT have been part of the MRV since 2025, it is still unclear whether and when the emissions of these ships will also be priced. This is expected to be decided in 2026 as part of a major EU ETS review.

In addition to the gradual introduction of several ship and emissions categories, pricing will also be phased in over a three-year period. From 2024, affected shipping companies will have to surrender EUAs for 40% of their verified emissions, 70% in 2025 and 100% from 2026 (Figure 2).

EU ETS maritime implementation period

Figure 1: EU ETS maritime implementation period (source: carboneer according to EU Commission)

Responsibilities and ISM delegation

The obligated ‘shipping company’ within the meaning of the EU ETS Directive is, by default, the registered shipowner. The shipowner may contractually delegate the EU ETS obligations to the company that is responsible for ship operations under the International Safety Management (ISM) Code. A prerequisite for delegation is that a proper and complete mandate agreement in accordance with the detailed requirements of Implementing Regulation (EU) 2023/2599 has been submitted to the competent authority (source: DEHSt). The mandate agreement must document the assumption of all EU ETS obligations and be submitted to both the administrative authority and the verification body. Bareboat charters can only act as shipping companies if they are also ISM companies. The company responsible for MRV of emissions and the obligations under the EU ETS must always be identical. In practice, this requirement poses considerable challenges, as many shipping companies operate their fleets through multiple ISM managers who use different management and emission measurement procedures.

Annual obligations

The annual compliance cycle of the EU ETS for shipowners and ISM companies follows a clearly structured annual rhythm that begins even before the first port call. Before operations commence, an approved monitoring plan must be in place, which is reviewed by an accredited verifier and approved by the competent administrative authority (source: EU Commission). The verified plan must be submitted to the competent administrative authority via the THETIS MRV portal by 1 April 2024 at the latest or within three months of the first port call under EU jurisdiction. Throughout the reporting year, ships continuously record their greenhouse gas emissions using the methods defined in the monitoring plan.

By 31 March of the following year at the latest (Figure 3), this data must be verified and include both a ship-level emissions report and a company-level emissions report, which are generated via the THETIS-MRV portal.

Compliance cycle in the EU ETS (source: carboneer)

Figure 3: Compliance cycle in the EU ETS (source: carboneer)


A Document of Compliance can then be created via THETIS-MRV, which must be carried on all affected ships of the relevant company. In order to have sufficient buffer for any corrections, verification should begin promptly after the start of the year. Once the shipping company has assigned the verifier to the Union Registry, the verifier can confirm the verified emissions directly in the Maritime Operator Holding Account (MOHA) in the Union Registry.

At the same time, affected companies use the MOHA to purchase, trade and submit EUAs. The central compliance deadline for the year is 30 September. By this date, sufficient EUAs must be submitted via the MOHA in the Union Registry to cover the verified company emissions. To ensure that the reporting, verification and submission processes run smoothly, a tight internal schedule is recommended: continuous monitoring, early data validation by verification bodies, timely entries in THETIS-MRV and the Union Registry, and timely procurement and provision of the required EUAs.

Sanctions and measures by authorities

In the EU ETS, violations of the obligation to surrender EUAs by 30 September of each year are subject to a fine. The penalty payment is €100 per tonne of CO₂ equivalent for emissions caused in the previous year for which no EUA was submitted. Since 2012, the value has been increasing annually in line with inflation, meaning that violations in 2024 will incur a penalty of €132.06 per tonne of CO₂ equivalent (source: DEHSt). Regardless of the penalty payment, the obligation to retroactively purchase and submit the missing EUAs remains. Similarly, if EUAs are not submitted, the names of the defaulting shipping companies are for exampled published in the Federal Gazette of Germany once the decision has become final; at EU level, the Commission also maintains an annual list of non-compliant operators.

This ‘naming and shaming’ increases the reputational risk, and in the event of repeated violations in two or more reporting periods, the flag or port state authorities may, as the most severe measure, deny access to EU ports or also detain ships in the home port of an EU state. Since liability applies company-wide, a single ship violation can affect the operator’s entire fleet (source: DEHSt). Consistent measurement of emissions, timely verification and timely procurement and submission of EUAs therefore remain essential to avoid financial penalties and operational restrictions. In the second part of our series, we will look at price and market developments in the EU ETS, the cost implications for shipping companies and the complementary rules under the FuelEU Maritime Regulation.

Sources

DEHSt, 2025, EU Emissions Trading 1 for Maritime Transport, URL: https://www.dehst.de/EN/Topics/EU-ETS-1/Maritime-Transport/EU-ETS-1-Maritime-Transport/eu-ets-1-maritime-transport_node.html

DEHST, 2025, EU ETS 1 Sanctioning, URL: https://www.dehst.de/EN/Topics/EU-ETS-1/EU-ETS-1-Information/Sanctioning/sanctioning_node.html

DEHSt, 2025, Maritime Transport-FAQ, URL: https://www.dehst.de/SharedDocs/FAQ/EN/maritime-transport/FAQList-SV.html#faq-id-299956

EEA, 2025, EU Emissions Trading System data viewer, URL: https://www.eea.europa.eu/en/analysis/maps-and-charts/emissions-trading-viewer-1-dashboards

EMSA, 2025, Facts and Figures, URL: https://emsa.europa.eu/publications/item/4515-emter-facts-and-figures.html

EU, 2024, Kommission Implementing Decision EU) 2024/411, URL: https://eur-lex.europa.eu/legal-content/EN/TXT/PDF/?uri=OJ:L_202400411

EU Kommission, 2025, FAQ – Maritime transport in EU Emissions Trading System (ETS), URL: https://climate.ec.europa.eu/eu-action/transport-decarbonisation/reducing-emissions-shipping-sector/faq-maritime-transport-eu-emissions-trading-system-ets_en

EU Kommission, 2025, Report from the Commission: Review of Regulation (EU) 2015/757 on the monitoring, reporting and verification of greenhouse gas emissions from maritime transport in relation to the potential inclusion of ships below 5 000 gross tonnage but not below 400 gross tonnage  , URL: https://eur-lex.europa.eu/legal-content/EN/TXT/PDF/?uri=CELEX:52025DC0109

EU Kommission, 2025, Monitoring, reporting and verification URL: https://climate.ec.europa.eu/eu-action/eu-emissions-trading-system-eu-ets/monitoring-reporting-and-verification_en

Effective CBAM Cost Management (Part 1): CBAM Certificate Demand and Explicit Costs

In the first part of a series on effective CBAM cost management, we use a specific case study to derive the CBAM certificate requirements and the resulting explicit costs. Importers of CBAM goods may already incur high costs for imports in 2026 and should prepare for this at an early stage.

Assessing the financial impact of CBAM

While only reporting obligations apply for importers or indirect customs representatives in 2025, CBAM will enter the regular phase from 2026 (review our article on CBAM here). Above all, this means that, in addition to continuing to report imported goods and corresponding emissions, authorised CBAM declarants will have to acquire CBAM certificates for the embedded emissions contained in the imports from 1 January 2026 and submit them annually by 31 August of the following year. From the perspective of an importer or indirect customs representative, this has strategic relevance and the impact on risk and liquidity management of this additional financial burden should therefore already be analysed in 2025 in order to:

  • Plan a budget for the procurement of CBAM certificates
  • Develop a purchasing strategy for the acquisition of CBAM certificates
  • Manage or hedge price uncertainties of CBAM certificates and thus costs for imported goods
  • Adapt supplier and customer contracts to avoid being stuck with CBAM costs
  • Integrate the effects of CBAM into strategic purchasing decisions

The steps for developing a targeted strategy for CBAM cost management are described below using a case study. The starting point is to determine the relevant CBAM emissions, as this determines the quantity of CBAM certificates to be purchased. The following formula shows the most important parameters. To simplify matters, the assumption here is that no CO2 prices were paid in the upstream supply chain.

Calculation of the demand for CBAM allowances and relevant data sources (without taking into account CO2 prices in the upstream supply chain)

Figure 1: Calculation of the demand for CBAM allowances and relevant data sources (without taking into account CO2 prices in the upstream supply chain)

In addition to the information on the imported products and the embedded emissions they contain, the CBAM benchmarks are particularly relevant for calculating the quantity of CBAM certificates to be purchased. The CBAM benchmarks are expected to be published in Q4 2025. and will be based on the benchmarks for determining the free allocations in the EU Emissions Trading System (EU ETS). The CBAM benchmarks will therefore only be officially announced relatively shortly before the date on which CBAM allowances are purchased. However, a scenario analysis can already be used today to estimate the CBAM certificate requirement with the aid of the corresponding EU ETS benchmarks.

Analyse of the CBAM certificate demand

To illustrate the approach, the following case study uses an annual import volume of 100,000 tonnes of steel ingots in equal parts each quarter. Other important assumptions for modelling the CBAM certificate demand are:

  • No deductible CO2 prices in the upstream supply chain
  • Direct specific emissions: 2.58 tCO2/tproduct
  • Indirect specific emissions: 0.43 tCO2/tproduct
  • Use of a combination of EU ETS benchmarks as a proxy for the CBAM benchmark
  • Inclusion of indirect emissions from 2030 (envisioned in the CBAM Regulation, not yet part of the legal text)

The quantity of CBAM certificates to be purchased annually for the CBAM declarant in the case study is shown below. The importer must purchase over 130,000 CBAM certificates for its imports in 2026, which corresponds to pricing of 50 % of the imported direct specific emissions. This means that a significant proportion of embedded emissions could be priced right from the start of the CBAM definitive phase. This depends in particular on the level of embedded emissions in the imported CBAM goods and therefore on the CO2 intensity of the production process of the corresponding manufacturer. An analysis per import unit, CBAM product and supplier can provide information on important metrics such as the absolute and relative contribution to the need for CBAM certificates.

Estimation of CBAM certificate demand for 2026-2034 with import of 100,000 tonnes of steel ingots per year
Figure 2: Estimation of CBAM certificate demand for 2026-2034 with import of 100,000 tonnes of steel ingots per year (source: carboneer CBAMCC model)

Important: The quantity of CBAM certificates that must be held by CBAM applicants for imported goods is 50% of the imported emissions since the beginning of the year at the end of each quarter (final decision still pending), with an exemption to this rule for imports in 2026, as CBAM certificates can only be purchased from 2027 onwards. However, the actual quantity of CBAM certificates to be submitted is ultimately based on the verified embedded emissions of the imported goods or the standard values of the EU Commission that are yet to be published. This difference between verified emissions values and default values can be significant in some cases. A precise analysis of the relevant imports and associated embedded emissions is essential for estimating the need for CBAM allowances from 2026 onwards.

Cost estimate and liquidity demand for CBAM certificates

The annual costs for CBAM certificates assuming constant import volumes in our case study can now be estimated. Forecasts and scenarios for emission allowance (EUA) prices in the EU ETS can be used for this purpose, as CBAM allowance prices for imports from 2027 are formed on a rolling basis by the weekly average of EUA auction prices (currently at around 70 EUR/tCO2). The carboneer CBAMCC model uses price projections from various publications for this purpose. The projected costs for the CBAM certificates for constant annual imports are shown below; the uncertainty factor due to uncertain price developments in the EU ETS is illustrated by the bars.

Forecast of CBAM certificate costs for 2026-2034 for imports of 100,000 tonnes of steel ingots per year

Figure 3: Forecast of CBAM certificate costs for 2026-2034 for imports of 100,000 tonnes of steel ingots per year (source: carboneer CBAMCC model)

The liquidity requirement for CBAM certificates for the importer or CBAM applicant in the case study increases from around EUR 10 million for imports in 2026 to EUR 25-45 million in 2030. CBAM certificates are neither tradable between companies nor valid in the long term. CBAM certificates purchased under the 50% holding requirement in the previous year can be sold back to the regulatory authority, while excess CBAM certificates will be cancelled on 1 October of the second year after purchase without compensation (final decision still pending). Obligated companies should therefore prepare to understand the financial impact of CBAM.

In our next article, we will go into detail about the options available to importers to manage risk and hedge their CBAM certificate costs.

The EU ETS 2 – pricing emissions in buildings and road transport

The European Union’s Emissions Trading System (EU ETS) constitutes a cornerstone of the EU’s strategy to combat climate change since its establishment in 2005. The new EU ETS 2, implemented from 2024 covers emissions from buildings, road transport, and additional sectors such as fuel use in small industrial installations. The EU ETS 2 is founded upon the objectives of the EU Climate Law and the Fit-for-55 package and requires the fuel suppliers to monitor and report emissions in their fuels. From 2027 when the EU ETS 2 is fully operational, emission allowances need to be purchased and surrendered based on the emissions in the fuels sold. This new emission trading system adds a further layer of complexity to the regulatory compliance landscape.

Key facts about the EU ETS 2

The EU ETS 2 will be running in parallel to the EU ETS 1 and encompasses areas that were previously excluded, such as the buildings and road transport sectors. The operational principle of the EU ETS 2 is based on a cap-and-trade system, where an annually decreasing cap is set on total emissions and a corresponding number of allowances is auctioned to regulated entities. One allowance needs to be surrendered per ton of CO2 emitted. The EU ETS 2 is designed to reduce emissions by 42% by 2030 in comparison to 2005 levels. In contrast to the EU ETS 1, which regulates emissions at the point of origin, the EU ETS 2 places the compliance burden upstream at the release for consumption of fuels and not at the point where fuels are combusted. Estimates of the EU Commission expect up to 11.400 fuel suppliers, distributers and resellers to be regulated (regulated entities). This new system harmonises national and EU responsibilities, targets and emissions pricing.

To determine emissions under the scope of the EU ETS 2, a comprehensive monitoring, reporting, and verification (MRV) system is implemented at the company-level. To avoid double counting, emissions from fuel combustion under the EU ETS 1 should not be counted in the EU ETS 2. This requires fuel suppliers and their clients to provide proof and documentation in such cases. The EU ETS 2 permits the coexistence of national carbon taxes with the EU ETS 2, allowing EU Member States to exempt companies from EU ETS 2 requirements until 2030 if national measures are more stringent. In Germany the national ETS is only fully integrated into the EU ETS 2 from 2027 onwards, which makes a double reporting of emissions necessary for 2024 – 2026.

First compliance deadlines in 2024

For companies subject to the EU ETS 2, key compliance activities should already be ongoing, and deadlines are approaching soon. Companies must commence monitoring emissions by January 2024 and report those emissions by 30 April 2025. The timeline for compliance is stringent, as Figure 1 indicates.

Figure 1: Timeline of EU ETS 2 compliance obligations. Source: carboneer

To monitor emissions in accordance with the rules of the EU ETS 2, by 31 August 2024 a monitoring plan should be submitted to the competent national authority. Full compliance, especially procuring and surrendering allowances under the EU ETS 2 is required from 2027, and failure to meet these deadlines can result in significant penalties and legal repercussions, making it imperative for companies to commence preparations without delay. The potential consequences of non-compliance include financial penalties and loss of competitiveness.

From 2027 onwards allowances under the EU ETS 2 will be auctioned. An allocation of free allowances such as during the start of the EU ETS 1 and currently still applied to EU industry will not exist. To regulate the supply of allowances and maintain price stability, a market stability reserve will be implemented. The initial allowance cap in 2027 will be determined by applying a 5.1% annual reduction to the 2024 emission level. From 2025 onwards, this linear reduction factor increases to 5.38%. This implies that the total supply of allowances in 2027 will be approximately 1.25 billion, declining to below 800 million by 2030. Figure 2 illustrates the decline in the allowance auction volumes over time, aligned with the EU’s long-term sectoral climate targets.

Figure 2: Approximate EU ETS 2 allowance supply. Source: carboneer

Challenges and complexity

The EU ETS 2 presents a significant challenge for companies as they need to develop comprehensive emission monitoring plans, detailing their activities, fuel types, and emission calculation methodologies to comply with their obligations. Especially the calculation of the emissions can be a complex undertaking. First, a scope factor needs to be established to determine the portion of a company’s fuel sales that lie within the regulated activities, such as buildings and road transport. The scope factor ranges from 0 (no fuel in scope) to 1 (all fuel in scope). This ensures only relevant emissions are counted. Using the correct emission factor for different fuels along with the quantity of fuels, the total CO2-emissions can be calculated.

To ensure data quality, the MRV follows a tier system that categorises data accuracy from Tier 1 (least accurate) to Tier 4 (most accurate). Higher tiers, used for companies with more larger fuel streams and thus higher emissions, require more precise data, ensuring reliable results. Importantly, emissions from fuels based on biomass can be zero-rated if they fulfil the criteria on biomass under the Renewable Energy Directive (RED) II and the upcoming RED III.

Monitoring plans must gain approval from the competent national authority, underscoring the importance of early and thorough preparation. The emission reporting for 2024 is due 30 April 2025, with third-party verification becoming mandatory from the 2025 emission report on. The introduction of the EU ETS 2 pricing can result in significant cost increases, which will have an impact on both operational expenses and consumer prices. Figure 3 displays price forecasts for the allowances in the EU ETS from different sources. As prices are determined through demand and supply, they can be expected to exhibit significant volatility, with forecasts ranging from €48 to €340 per tCO2 by 2030. Companies ought to manage cost risk via tailored procurement strategies for EU ETS 2 allowances.

Figure 3: Forecast of EU ETS 2 allowances prices in 2030. Data Source: UBA, 2024, Source: carboneer


The Social Climate Fund plays a crucial role in mitigating the financial impact on vulnerable consumers in the EU. Its objective is to support vulnerable households and micro-enterprises that are impacted by the transition to a low-carbon economy. The fund, financed by revenues from the auctioning of allowances, provides financial assistance for measures that reduce emissions and energy costs. One example is the provision of subsidies to enhance the energy efficiency of residential properties such as improvements to insulation and the installation of more efficient heating systems. This dual focus on households and businesses ensures a broader impact, promoting social equity and economic resilience, and helps to offset some of the financial burdens and operational challenges posed by the EU ETS 2.

To understand the potential impact of the rising allowance prices, Figure 4 illustrates how different fuel types are being impacted by different allowance prices.

Figure 4: Price impact on different fuels under varying EU ETS 2 allowance prices. Source: carboneer

What should an EU ETS strategy entail?

Due to the complexity of the EU ETS 2 and its stringent timeline, a sound EU ETS 2 strategy is essential. But what does a company need to prepare for?

MRV details and compliance cycle

  • Development of comprehensive monitoring plans that cover all relevant activities, fuel types, and emission calculation methodologies
  • Monitoring plans must be approved by national authorities
  • Verification of emissions

Compliance obligations:

  • Detailed understanding of the EU ETS 2 rules and associated regulation
  • Build capacity, assign responsibilities, internal and external communication
  • Access to registries and EU ETS 2 allowances

Financial impact assessment:

  • Assessment of EU ETS 2 exposure and cost forecasts
  • Implementation of strategies to manage costs and pass on costs to consumers
  • Risk management and allowance procurement strategies to reduce financial exposure

Conclusion

The EU ETS 2 is a crucial tool in the European Union’s strategy to combat climate change by establishing a new cap-and-trade system for fuels in sectors such as buildings and road transport. It aims to reduce emissions by 42% by 2030 compared to 2005 levels. The system introduces complex obligation for companies that require planning and a compliance strategy, including stringent monitoring, reporting, and verification processes starting from 2024. With allowance prices expected to rise significantly, the financial implications are substantial and necessitate robust risk management and hedging strategies. Companies should act now to understand and navigate these new regulations, ensuring compliance and maintaining competitiveness.

Authors: Florian Schlennert and Simon Göß.

Sources: UBA, 2024, Supply and Demand in the ETS 2, URL: https://www.umweltbundesamt.de/publikationen/supply-demand-in-the-ets-2


Carbon management in Germany (II): emissions, potentials, and costs for CCUS

In this second article of the series on carbon capture, use and storage (CCUS) in Germany, carboneer analyses the emission profiles of German industries and associated CCS potentials and costs. Review the first article on the developments around carbon management in Germany from a political and climate perspective here. Follow carboneer to access all articles, covering the general historical and political context of the topic, and highlighting developments and implications for the sectors steel, cement, lime, chemicals, and waste incineration.

Focus on industrial emissions

The energy sector, specifically electricity generation in coal and gas power plants, will most likely be excluded from any CCUS activities as the Carbon Management Strategy (CMS) of Germany is geared towards residual (hard-to-abate) and process-related emissions in the industrial sector. Still, the energy sector is the largest contributor to German CO2 emissions: In 2021 the energy sector emitted 238 Mt of CO2, accounting for 35% of total CO2 emissions. Most of the emissions from existing coal and gas power plants are however expected to be replaced by renewable sources or green hydrogen utilization, therefore limiting the scope for CCUS applications. Some potential however remains, mostly through CCUS applications in waste and biomass power plants.

The focus for CCUS activities will thus be on the industrial sector, the second largest contributor to CO2 emissions in Germany. In 2021, industrial facilities were responsible for 168 Mt of CO2 emissions, accounting for 25% of total CO2 emissions. The largest share of industrial emissions originates from large installations that are subject to the EU Emission Trading System as well as from waste incineration facilities. These installations emitted a total of 137.8 Mt CO2 in 2021 (cf. Figure 1), with largest contributions from steel production (31.5 Mt), waste incineration (23.3 Mt), cement production (20.1 Mt), the production of chemicals (16.9 Mt), and lime (6.4 Mt).

Figure 1: Sectoral shares of German industry (EU ETS facilities) and waste incineration CO2 emissions in 2021 (source: carboneer, data sources: DEHSt (2022), EEA (2022))

The CCS potential in the industrial sector in Germany

Three quarters of emissions in the industry are related to energy use and are to be abated using renewable energy. Approximately one quarter of the industrial emissions are process-related and originate from the utilization of carbon-containing materials in production. Process-related emissions are difficult to avoid and the five major climate neutrality studies for Germany (see part I) highlight the significant role of CCUS for emission mitigation or CO2-recycling in industry.

When calculating the CCS potential, it is important to notice that not all process-related emissions can be captured. Depending on industry and the dispersion of emission sources, the share of capturable emissions ranges from 45% in the chemical industry to 90% for waste incineration facilities. Following this methodology, the amount of technically capturable CO2 emissions from large industrial and waste incineration facilities in Germany amounts to 44.2 Mt (cf. Figure 2).

Figure 2: CCS potential in selected industrial sectors in Germany (source: carboneer)

Considering economic feasibility and alternative technological pathways for decarbonization, the ultimately relevant CCUS potential shrinks even further. While lime, cement, and waste incineration will need to capture CO2 due to a lack of technological alternatives, the use of green hydrogen may be the primary decarbonization route for steel production. The chemical industry will continue to depend on carbon-containing materials to produce basic chemicals, but might shift from fossil to biogenic and atmospheric sources, or build on recycled carbon from other industrial sectors. A more detailed analysis of the different sectors and their CCUS readiness will follow in future articles of this series.

Infrastructure and costs

To enable the transport of captured CO2 to potential storage sites or consumers, suitable infrastructure is necessary. The development of CO2 transport infrastructure is critical for the success of carbon management, and the pace of its development can significantly influence the entire progress of CCUS applications. By 2030, first large-scale CO2 transport infrastructures in Germany are necessary, where the mode of transport will depend on the scale and intended use of the CO2. Rail, trucks, ships, and pipelines can all be viable options. A pipeline connection is particularly useful for large industrial sites and CCUS clusters that generate significant amounts of CO2 to be transported over longer distances to storage facilities. However, for decentralized sites such as lime and cement plants, the most efficient handling of captured CO2 has yet to be identified. Local production of synthetic fuels is one of the possible options. A country-wide CO2 pipeline system connecting all major point sources is unlikely to develop, but pipelines for large industrial clusters will be necessary in the medium to long term. Furthermore, some oil and gas companies are already working on developing pipelines for exporting CO2 generated in Germany to storage sites in the North Sea.

While CCS costs (including capture, transportation, and storage) are relatively homogeneous across sectors, the current unavailability of storage capacity within Germany makes pure CCS implementation relatively expensive (cf. Figure 3) when compared to a country such as the United Kingdom, which has better access to storage sites (e.g. the North Sea). High costs of approximately 200 EUR/t CO2 for CCS applications in Germany already point at the need for incentive and support mechanisms to bring carbon management to an industrial scale.  

Figure 3: Average CCS cost in EUR/t CO2 in Germany and the UK (source: carboneer, data source: CATF, 2022)

Policymakers in Germany have to make the decision whether depleted natural gas reservoirs and saline aquifers in northern Germany and under the German North Sea are suitable CO2 storage sites, or if exporting CO2 through international collaborations and storing it in the North Sea and Norwegian Sea is a more politically acceptable option.

In the upcoming articles of this series, we investigate the attractiveness and readiness of the above industrial sectors for CCS applications based on indicators such as the regulatory framework, competing decarbonization options and other sector specific characteristics.

This article is based on a study by carboneer for the Trade Commissioner Service of the Canadian Embassy to Germany.

Sources

CATF (2022) The cost of carbon capture and storage in Europe. Available at: https://​www.catf.us​/​ccs-​cost-​tool/​ (Accessed: 27 March 2023).

DEHSt (2022) Treibhausgasemissionen 2021: Emissionshandelspflichtige stationäre Anlagen und Luftverkehr in Deutschland (VET-Bericht 2021). Available at: https://​www.dehst.de​/​SharedDocs/​downloads/​DE/​publikationen/​VET-​Bericht-​2021.pdf​?​__blob=​publicationFile&​v=​7 (Accessed: 27 March 2023).

EEA (2022) Industrial Reporting database, May 2022, 7 March. Available at: https://​www.eea.europa.eu​/​data-​and-​maps/​data/​industrial-​reporting-​under-​the-​industrial-​6 (Accessed: 27 March 2023).

Carbon management in Germany (I): from zero to climate and industrial necessity

This is the first article of a series on the potential of carbon capture, use and storage in Germany that will be published by carboneer over the coming weeks.

In this article, we look at the implications of a climate neutral Germany in 2045 on the demand for carbon management and carbon capture use and storage (CCUS). The topic has long been neglected in public debates but experiences a recent revival. CCUS can serve the dual purpose of (i) supporting the decarbonization of industrial facilities, and (ii) supplying especially the chemical sectors with CO2 as a resource for the production of primary products.

A brief history of carbon capture policy in Germany

While research on large-scale underground CO2 storage started in 2004 at the Ketzin pilot site close to Berlin, industrial carbon management activities (carbon capture, utilization and storage – CCUS) are virtually absent in Germany to the present. The European Union’s Carbon Capture and Storage Directive from 2009 provided its Member States with a framework to implement corresponding national legislation. The German Carbon Dioxide Storage Act (Kohlendioxid-Speicherungsgesetz – KSpG) came into force in August 2012 (cf. figure 1) but failed to establish favourable conditions for CCUS applications.

The storage discussion at that time in Germany was closely linked to the continuation of coal power generation and met strong public resistance. The expansion of renewable energy generation was at the center of potential mitigation pathways and CCUS applications were considered risky especially with regards to cost and safety criteria. Giving in to the general scepticism, the KSpG only allowed for applications with storage capacities below 1.3 million tons of CO2, and most states prohibited underground CO2 storage. No single storage project has been developed until the legal deadline for project submissions by the end of 2016. Currently it is therefore not possible to store CO2 underground in Germany and only a limited amount of capture and utilization projects are operative.

Carbon management has reemerged in the political arena in Germany only recently. The northwestern industrial state of North Rhine-Westphalia published its Carbon Management Strategy in 2021 and the National Carbon Management Strategy is currently being developed by the Federal Ministry for Economic Affairs and Climate Action (BMWK). We covered the national German Carbon Management Strategy in detail in this article.

Figure 1: Timeline and relevant events on carbon management in Germany (source: carboneer)

Carbon Management is a central component of climate neutrality

With tightening climate targets at EU and German level, it is becoming increasingly clear that climate neutrality by mid-century or even 2045 will not be achieved without large-scale capture, utilization and long-term storage of CO2. 

While CCUS experienced a slow uptake in German policymaking, academic research unanimously concludes that carbon management, including carbon capture, utilization and storage, as well as atmospheric carbon removal are necessary to reach climate targets. Since the electricity sector can be largely decarbonised through the expansion of renewables, the focus of carbon management in Germany lies on the industrial sector. Especially process-related emissions are hard to abate and might only be reduced through carbon capture solutions. Figure 2 shows the projections of five research projects on the sources of the CO2 that will be captured in 2045, at the time when Germany seeks to achieve climate neutrality.

Figure 2: CO2-capture according to application and source in 2045 (2050 for BMWK) (source: carboneer, data sources: Agora: Prognos, Öko-Institut, Wuppertal-Institut (2021), BDI: BCG (2021), dena: Deutsche Energie-Agentur (2021), BMWK: Fraunhofer ISI et al. (2022), Ariadne: Luderer, Kost and Sörgel (2021))

Building up the capacity to capture between 35 and 70 Mt of CO2 from different industries, or 5-10% of current German GHG emissions, requires targeted and substantial investments over the coming two decades. Investments will only materialize if determined policy making creates an enabling investment environment and delivers clear rules and guidelines on topics such as:

  • Incentive mechanisms for capture, utilization and storage
  • Transport and storage infrastructure provision and regulation
  • Regulation of CO2 imports and exports
  • GHG accounting (especially in utilization projects)

From waste to resource: how much storage is actually needed?

While we will take a deep dive into different industrial sector’s CCUS conditions and dynamics in upcoming articles of this series, we already want to draw your attention to some insights from our latest analysis. The technical potential across German industries predestined for CCS applications (steel, cement, lime, chemicals, waste incineration) amounts to 40-50 Mt CO2. Here we consider process-related emissions only, as other emission can and must be decarbonised through other solutions, such as renewable energy, electrification, or green hydrogen.

On the other side, the demand for carbon in the chemical industry in Germany in 2045 is estimated to be approximately 50 Mt CO2. This already points to a new paradigm and an industrial ecosystem, where CO2 will not necessarily be sequestered and stored underground in northern Germany, under the North Sea or even being exported to Norway, Denmark, or the Netherlands. Quite the opposite, CO2 might become a scarce a raw material in the industrial carbon cycle pushing the demand for CCU applications. Furthermore, the updated regulation on the EU Emission Trading System allows regulated entities to use CCUS instead of surrendering emission allowances. Undoubtedly, this option further increases the demand for CCUS applications.

Consideration of policy interactions and emerging new industrial paradigms are crucial for a successful carbon management at the national and EU level. Topics that require further analysis are amongst others:

  • Necessary CO2 transport capacity within Germany and Europe
  • Ultimate storage capacities needed across Europe
  • Quality criteria of CO2 for transport and utilization
  • Build-up of capture, transport and storage capacities in sync
  • Development of industrial carbon management clusters

The next article in this series on carbon management in Germany will deal with the current industrial emissions, the CCS potential in those industries and cost estimates for capture, transport, and storage. In the meantime, feel free to reach out with feedback and questions, which we are happy to discuss.

This article is based on a study by carboneer for the Trade Commissioner Service of the Canadian Embassy to Germany.


Sources:

BCG (2021) Klimapfade 2.0: Ein Wirtschaftsprogramm für Klima und Zukunft, Gutachten für den BDI. Available at: https://​web-assets.bcg.com​/​58/​57/​2042392542079ff8c9ee2cb74278/​klimapfade-​study-​german.pdf (Accessed: 25 March 2023).

Bundesregierung (2022) Evaluierungsbericht der Bundesregierung zum Kohlendioxid-Speicherungsgesetz: Drucksache 20/5145. Available at: https://​dserver.bundestag.de​/​btd/​20/​051/​2005145.pdf.

Deutsche Energie-Agentur (2021) dena-Leitstudie Aufbruch Klimaneutralität: Eine gesamtgesellschaftliche Aufgabe. Available at: https://​www.dena.de​/​fileadmin/​dena/​Publikationen/​PDFs/​2021/​Abschlussbericht_​dena-​Leitstudie_​Aufbruch_​Klimaneutralitaet.pdf (Accessed: 27 March 2023).

Fraunhofer ISI, Consentec and ifeu (2022) Langfristszenarien für die Transformation des Energiesystems in Deutschland: Modul 3: Referenzszenario und Basisszenario, Studie im Auftrag des Bundesministeriums für Wirtschaft und Energie. Available at: https://​www.langfristszenarien.de​/​enertile-​explorer-​en/​ (Accessed: 25 March 2023).

Luderer, G., Kost, C. and Sörgel, D. (2021) Deutschland auf dem Weg zur Klimaneutralität 2045 – Szenarien und Pfade im Modellvergleich: PIK: Potsdam-Institut fur Klimafolgenforschung. Available at: https://​policycommons.net​/​artifacts/​1860013/​deutschland-​auf-​dem-​weg-​zur-​klimaneutralitat-​2045/​2607518/​ (Accessed: 28 March 2023).

Prognos, Öko-Institut, Wuppertal-Institut (2021) Klimaneutrales Deutschland 2045. Wie Deutschland seine Klimaziele schon vor 2050 erreichen kann: Zusammenfassung im Auftrag von Stiftung Klimaneutralität, Agora Energiewende und Agora Verkehrswende. Available at: https://​www.agora-energiewende.de​/​veroeffentlichungen/​klimaneutrales-​deutschland-​2045 (Accessed: 25 March 2023).

Carbon Management and CCU/S in Germany

The German government is currently developing a Carbon Management Strategy for CO2 storage and utilisation. Because, one thing is indisputable: Without the capture, use and storage of CO2 from industrial processes (CCU/S) and the atmosphere, Germany can hardly become climate neutral by 2045. The basis for the Carbon Management Strategy is the new evaluation report on the Carbon Dioxide Storage Act. In this article, we explain the key points and principles of such a strategy.  

The CCU/S nomenclature

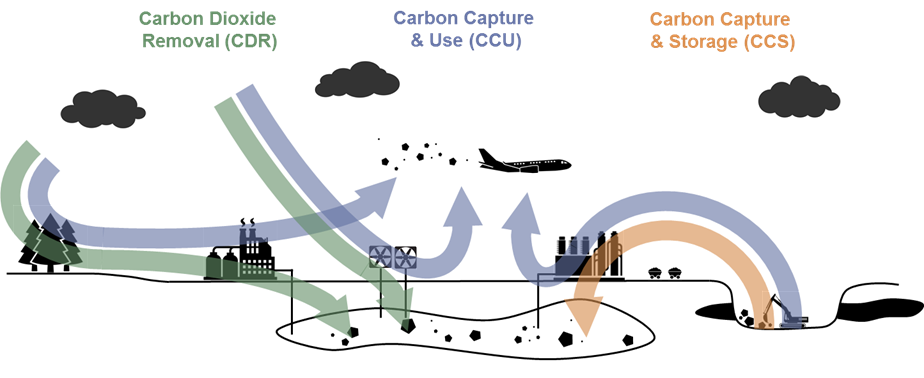
For the purposes of consistent nomenclature, we use the term carbon management below as an umbrella term for carbon management that includes CO2 capture, transport, and use (CCU) or storage (CCS) from fossil as well as biological or atmospheric sources as negative emissions or carbon dioxide removal (BECCS and DACCS). Likewise, dealing with other nature-based solutions to remove and reduce greenhouse gas emissions from the atmosphere is part of carbon management (see Figure 1).

Diagram

Description automatically generated
Figure 1: Sources and sinks of CO2 emissions of the different components of carbon management (source: carboneer).

The impact on the climate and the technical and economic details of the different technologies and options are complex and require detailed analysis. Feel free to contact us for more information.

Carbon management necessary for climate neutrality

In early January 2023, German Economics Minister Robert Habeck travelled to Norway to explore further cooperation in the field of energy and climate. Among other things, the topic of CO2 capture, transport and storage is to become an important part of the cooperation with Norway. With tightening climate targets at EU and German level, it is becoming increasingly clear that greenhouse gas or climate neutrality by mid-century will not be achieved without large-scale capture, utilisation and, above all, long-term storage of CO2. 

At the same time, the German Federal Ministry of Economics and Climate Protection (BMWK) published the German government’s evaluation report on the Carbon Dioxide Storage Act (KSpG) in December 2022. The KSpG came into force in August 2012 and was intended to test the first demonstration projects for the long-term storage of CO2 in the ground in Germany. Acceptance of CO2 storage in Germany has always been very low in the past, especially as the discourse was strongly linked to the use of CO2 capture at coal-fired power plants and the continued operation of coal power plants. However, by the end of the application deadline for approval of new underground CO2 storage facilities (end of 2016), only one demonstration project had been applied for and been built in Germany. Since no new applications can be submitted after the end of 2016, underground CO2 storage is de facto not possible throughout Germany.

CO2 capture for residual emissions in industry

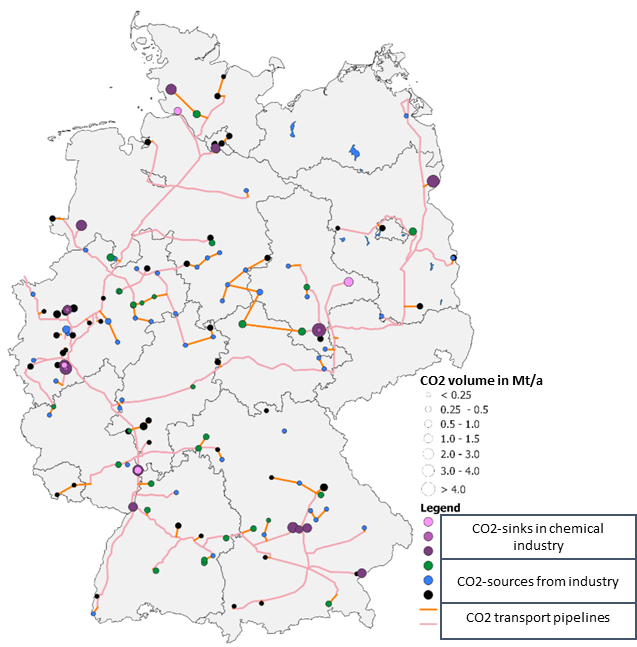
In the future, the use of CCS at coal-fired power plants in Germany is not expected to play a role due to the planned phase-out of coal. Capture, utilisation or storage of CO2 will however be needed primarily for a climate-neutral industry. Even after the use of renewable energies or electrification, large quantities of process-related CO2 emissions will still be produced, for example in the lime and cement industries or in the steel industry. Carbon is also the starting point for many other important products in the chemical industry and is therefore also needed as a raw material. The long-term scenarios project assumes that around 30 million metric tons of CO2 will have to be captured, transported, reused or disposed of in final storage by industrial plants in Germany even after climate neutrality has been achieved in 2045. Possible locations of capture plants and transport pipelines for CO2 are shown in Figure 2. 

Figure 2: Possible CO2 sinks, sources and transport pipelines in Germany in 2045 (source: Langfristszenarien)

Here, it is noticeable that clusters of CCU/S sites are located in the core areas of German basic and heavy industry. This clustering is mainly due to economic economies of scale for infrastructures for capture, transport but also the potential reuse of CO2. Accordingly, the focus of the German Carbon Management Strategy will be primarily on the industrial sector and not on capture in coal-fired power generation.

In addition to the capture of CO2 at industrial sources, however, the use of carbon removal solutions, i.e., the physical removal of CO2 emissions from the atmosphere, must also be developed. Carbon removal is the only way to offset the greenhouse gas emissions that will continue to occur in 2045, for example from agriculture. At 45-80 million metric tons of CO2, the negative emissions required are actually at a higher level than CO2 emissions to be captured from industrial processes. We have presented the details here and here.

Key principles of the German carbon management strategy

The use of CCU/S in industry will play a role as a decarbonisation option, alongside energy and resource efficiency and the use of green energy sources and electrification of processes. Key findings from the latest climate neutrality studies for Germany (Klimaneutrales Deutschland 2045, Klimapfade 2.0, dena-Leitstudie Aufbruch Klimaneutralität, Langfristszenarien) allow the following assessments:

  • Increase in ambition level of climate targets leads to increased use of CCU/S
  • CO2 capture in the million metric ton range necessary as early as 2030
  • Use of CCS mainly in industry and waste sector
  • Negative emissions from carbon dioxide removal must be scaled up from 2030 at the latest
  • Permanence of CO2 removal and storage by nature-based methods is uncertain and therefore makes technical solutions necessary as well
  • Fossil CCU/S and technical carbon dioxide removal can use the same infrastructures and should be considered in an integrated way
  • Transparent and continuous dialogue needed to ensure societal acceptance for ramp-up of CCU/S
  • Significant amounts of CO2 capture at global level (6-12 Gt/year depending on scenario) also driven by CCS at fossil power plants 

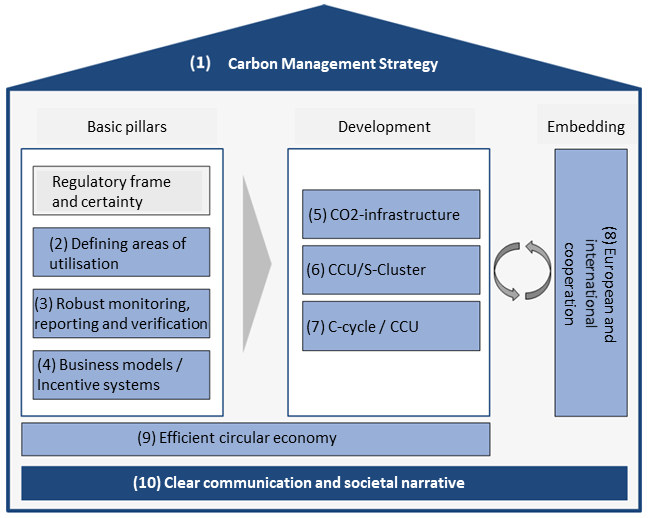
The recently published evaluation report on the KSpG provides the following key recommendations to the German government for revision: Examination and adjustment of regulations of the (cross-border) transport of CO2 and regarding German final storage sites for CO2, the further integration of CCU/S into the European Emissions Trading System (EU ETS), and the development of a clear framework for accounting of negative emissions. The details are to be elaborated in a German Carbon Management Strategy (Figure 3) by the German government, which will be presented during 2023. 

Figure 3: Basic pillars for carbon management in Germany (source: German government, adjusted by carboneer).

Which issues need to be clarified?

The German Carbon Management Strategy first aims to spell out a prioritisation of CCU/S applications. Questions must be answered for which industries and which emissions CCU/S measures are most important in order to use available resources in an appropriate manner. This should go hand in hand with the adaptation of the relevant regulatory framework, for example for approval procedures and the development and financing of (transport) infrastructures. Measures and funding programs in special application areas are also to be developed.

Methodologies for monitoring, reporting and verification (MRV) for CCU/S need to be developed. For example, the accounting of CCU/S in the EU ETS and the accounting for the use of CO2 from different sources (fossil, industrial cycle, biogenic, from the atmosphere) in the chemical industry and in the production of synthetic fuels must be clarified.

In particular, the possibility of transboundary CO2 transport will play a major role across the EU. In this regard, the Norwegian government has already made offers to the EU industry for accommodating their CO2 in underground storages in Norway. The design of pipeline and ship capacities as well as questions of EU network regulation and financing are important issues. The synergy effects of CCU/S clusters between industries as sources and sinks of CO2 must be elicited to find the most efficient solutions when planning infrastructures.

For possible CO2 storage facilities to become a reality also on German territory (probably rather under the seabed than under the mainland), social acceptance for CO2 capture and final storage must be built up. This can only happen through clear and transparent communication regarding the necessity of CCU/S for a climate neutral Europe and Germany.  

We will keep you up to date on the latest developments regarding the German Carbon Management Strategy. Please feel free to contact us if you have any questions on this topic.

What is the potential for negative emission technologies in Germany?

The updated German climate law requires negative emissions technologies (NETs) and carbon removal from the atmosphere (read all about that in our previous article). Here we want to answer the question, which of the solutions could be used in Germany and what their potential might be. The main take-away: Nature-based and technological carbon removal solutions will both be necessary at the Megatonne scale.

New studies confirm need for carbon removal

Two new reports that model pathways of how Germany can achieve climate neutrality by 2045 have been published in October 2021. The dena-Leitstudie “Towards Climate Neutrality” by the German Energy Agency and the Ariadne report as part of the Kopernikus Project funded by the German Ministry of Education and Research both make clear that substantial amounts of negative emissions are required to balance certain land use, agricultural or industrial emissions. Figure 1 extends our findings about how much annual negative emissions will be needed in Germany in 2045 including the data from the latest studies.

Figure 1: Required annual negative emissions in Mt CO2-eq in 2045 in Germany (source: cr.hub)

Generally, the latest numbers are similar to those from earlier studies. However the various studies still disagree on how much carbon Germany needs to remove from the atmosphere by a large margin. The resulting figures range between 40 and 100 Mt CO2-eq. The average between all studies points at annual carbon removal needs of a bit over 74 Mt CO2-eq at the point where Germany wants to be climate neutral.

Not only the scientific community alone is stressing the need of negative emissions, but increasingly industry groups and associations take the issue seriously. In a recent open letter to the new federal government a range of large corporations under the Stiftung 2 Grad stressed the need for developing a political framework for actively managing the carbon cycle and start developing solutions for capturing CO2 from industrial facilities and storing it underground (CCS).

Which negative emissions technologies are needed?

Broadly we can differentiate between nature-based carbon removal solutions and technological ones. The predominant nature-based solutions is re-, and afforestation, but also the renaturation of peatlands, the enhanced sequestration of carbon in soils through different agricultural practices or growing kelp in the sea fall into that category.

On the technological side, the main focus currently lies on DACCS (direct air capture and storage). Of course also hybrid solutions exist, such as BECCS (bioenergy with carbon capture and storage) or the production biochar which uses biomass and utilizes a technical process to sequester or bind the carbon in a non-reactive form.

We explain and compare a range of those NETs here. Figure 2 shows which of the various NETs are being foreseen to help Germany to achieve climate neutrality by 2045 based on selected studies. The answer to the question which NETs and carbon removal solutions are needed is simple: all of them!

Figure 2: Comparison of annual carbon removal capacity in MtCO2-eq of different NETs in recent reports for Germany in 2045 (source: cr.hub)

The different nature-based solutions are summarized into the land use, land use change and forestry (LULUCF) category in Figure 2, which takes up the largest share of necessary carbon removal in most studies and in many cases is not split up into more detailed removal pathways and sinks in the studies.

In addition, most studies foresee the need for substantial technical removals via BECCS and DACCS. Especially in case the nature-based solutions would not be able to deliver the large CO2-capturing capacities, technological solutions are required.

More exotic carbon removal solutions such as enhanced weathering do not feature prominently. The usage of carbon dioxide from the atmosphere as feedstock for green naphtha or methanol production and in long-lived plastic products goes into the 10 MtCO2-eq range. It is worth noting that the different studies do not necessarily agree on the potential or capacity of the different NETs. This is also due to the fact that not all studies consider the entire range of possible NETs or focus on specific technologies or sinks.

And just as a reminder: In 2018 the LULUCF sector in Germany only delivered 18 MtCO2-eq of negative emissions (source: dena). That means within the next 23 years a doubling to tripling of the annual carbon removal capacity through forests, swamp renaturation and soil carbon sequestration needs to be achieved. Otherwise the reliance on technological solutions that are as of now not scaled-up will be even higher.  

Negative emission potential in Germany

As seen above, a silver bullet or one NET to take out the excess carbon to make Germany truly climate neutral by 2045 does not exist. Much more, all solutions and technologies will be needed. To give a better overview of how such a carbon removal portfolio on the country level can look like, we used the numbers from the Ariadne project report and compared the potentials across the different NETs. Figure 3 shows the shares of different NETs in Germany in 2045 according to the report of the Ariadne project with a total potential of almost 110 MtCO2-eq.

Figure 3: Potential share of different NETs in Germany by 2045 according to the Ariadne project, light green wedge represent LULUCF (source: cr.hub)

The light green wedge taking 46 per cent of the total carbon removal potential represents the LULUCF sector, which can then further be split into re-and afforestation, soil carbon sequestration and carbon storage through changed agricultural practices such as agroforestry. Technological solutions such as BECCS and DACCS make up 37 per cent of the entire carbon removal potential, whereas biochar and enhanced weathering add up 17 per cent in total.

The way forward

The most recent results from climate and energy system modeling from a variety of different research groups are clear: Carbon removal from the atmosphere will be important for Germany to reach its climate targets. In 2045 the capacity to remove 10 per cent of the greenhouse gas emissions Germany emitted in 2020 from the atmosphere has to be in place.

That is not an easy feat, especially considering that carbon removal from the LULUCF sector today only has the capacity of providing a fifth to a quarter of the required negative emission capacity. In addition, climate change might impede the carbon storage capacity of nature-based solutions further during the coming decades. If natural carbon sinks cannot deliver, then technical or hybrid carbon removal solutions such as BECCS, DACCS or biochar become more relevant.

The most recent studies under consideration in this article arrive at different carbon removal capacity and needs for different NETs, as figure 2 demonstrates. Starting a structured conversation about how the recent reports arrive at their negative emission capacity for different technologies would be important. In that way science can develop an understanding about assumptions and the potential for an integral negative emissions modeling framework.

At the political level, devising a framework for active carbon management alongside capacity building measures and restarting a public dialogue on carbon removal and CO2-storage as necessary and important parts towards climate neutrality are the most important steps. Furthermore, a process on revising current regulations on CO2-storage and -transport, possibly across borders in a European context has to start. German climate targets should accommodate the differences between genuine emission reduction and carbon removal (as already being started in the UK and Sweden).

The take-away for the private sector: A new industry is forming and it needs to be scaled rapidly. Forward-looking companies and industries can be on the forefront of that development if they seize the opportunity. This holds for technology providers, project developers and emitting industries that can provide and utilise NETs. However, also companies with climate targets can demonstrate more credible climate action by neutralizing part of their difficult-to-abate emissions via negative emissions or carbon removal credits instead using less permanent and less credible offsetting projects.

We can help you to develop strategies concerning your climate targets and the role of negative emissions and provide you with insights into this new sector and market. Feel free to reach out for further discussions.

New German climate goal only possible with negative emissions?

Following the ruling of the Federal Constitutional Court in April 2021, the German government had to revise the Climate Protection Act. According to the revised law, Germany must be climate neutral as early as 2045 and greenhouse gas negative by 2050. These higher climate ambitions also mean earlier use of significant amounts of negative emissions. What changes have there been in climate legislation and what do the latest scenarios on carbon removal say for Germany?

As promised in our article on the global dimensions for negative emissions, this time around, we want to have a closer look at Germany. The country is touted for being one of the leaders in decarbonizing the energy system of an industrialised country both in terms of speed and scope. Renewable energies already make up 45 to 50 per cent of Germany’s electricity consumption with a goal to reach 65 per cent in 2030. 

Updated climate target requires climate neutrality by 2045

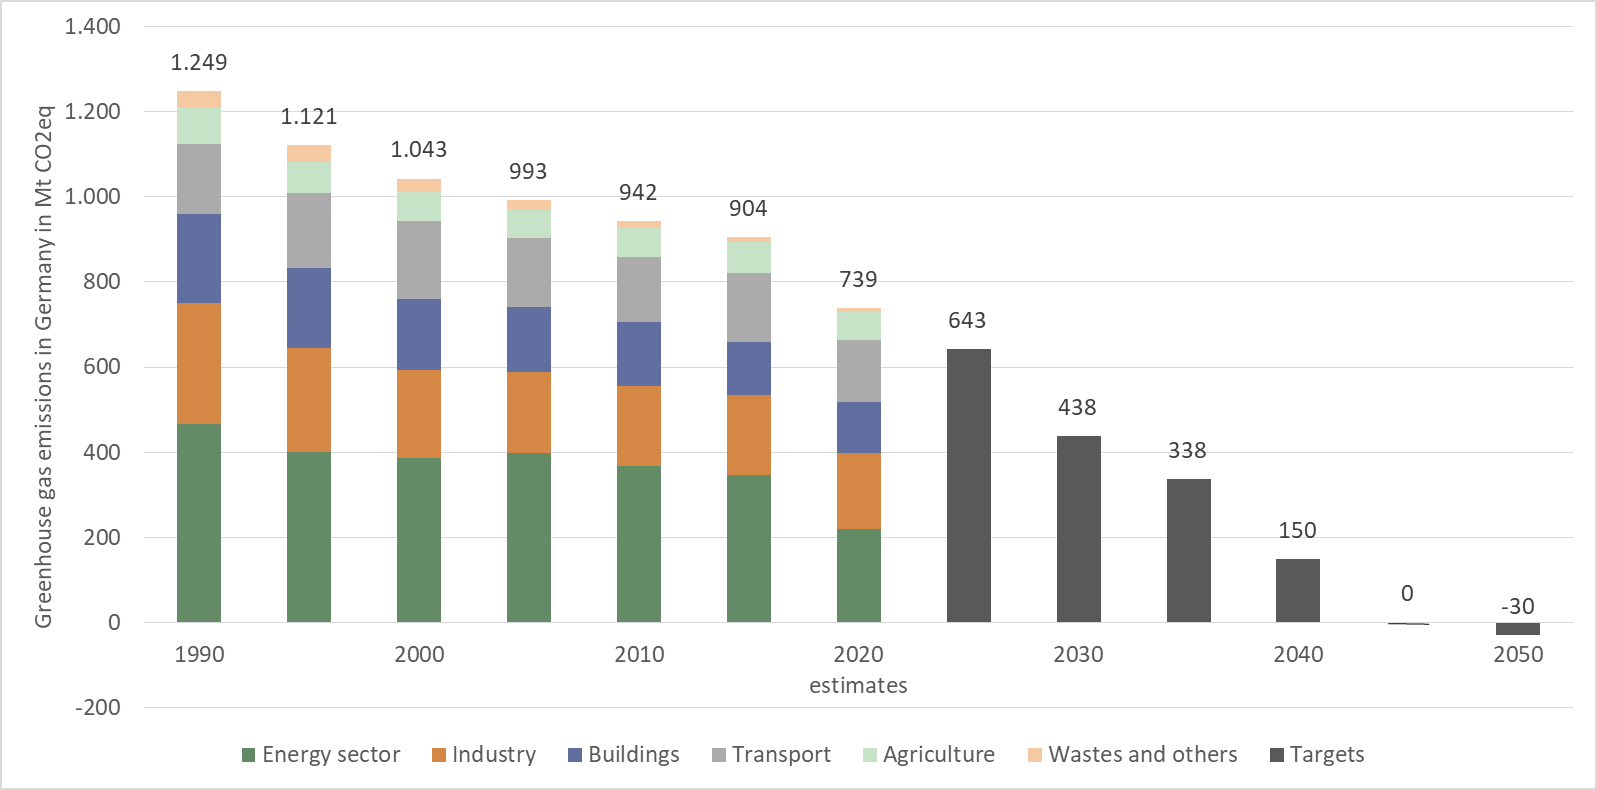
The German climate law has been revised in June 2021, after the Federal Constitutional Court required changes and more ambitious action. As a result the current government updated the country’s climate goals with an increased ambition towards climate or greenhouse gas neutrality by 2045. From 2050 onwards Germany is supposed to be greenhouse gas negative. Figure 1 depicts Germany’s historical emissions, the targets stipulated in the new law and potential negative emissions in 2050 according to the study Klimaneutrales Deutschland 2045 (Climate neutral Germany 2045) (data sources: BMU, UBA, Agora Energiewende).

Figure 1: Historic greenhouse gas emissions and targets for Germany in Mt CO2eq according to the new climate law and estimates for negative emissions by Agora Energiewende (source: cr.hub)

For 2021, Agora Energiewende expects the strongest annual increase in emissions since 1990, with a plus of almost 50 Mt (source: Agora Energiewende). This means that emissions this year could be back at the level of 2019 before Corona. The emission reduction of 40 per cent compared to 1990, which the country managed to achieve in 2020, would then be obsolete again.  

Are negative emissions part of the German climate strategy? 

A few years ago negative emissions or CCS were not part of the discussion concerning the climate and emissions reduction strategy in Germany, at least not on the policy level and only partially in the scientific context. This outlook changed:

  1. It is increasingly clear that emissions of greenhouse gases will remain in hard-to-abate sectors (such as industry and agriculture) even after strong emission reductions. 
  2. The current efforts of decarbonizing sectors other than the electricity sector, specifically buildings and transport is lagging behind and might not deliver the emissions reductions needed to even achieve the older and less ambitious climate targets. 
  3. Climate ambitions grew as the impact of a warming planet is already clearly visible and civil society demands more action. On the EU level the new target of 55 per cent emission reductions by 2030 compared to 1990 has been agreed on, and Germany followed suite with its new climate law.

Therefore negative emissions are more prominent in recent scenarios and studies on how Germany might be able to achieve its climate targets. On the policy level, they are only implicitly mentioned in the new climate law in terms of negative emissions in the Land Use, Land-Use Change and Forestry (LULUCF) sector. Concrete expansion targets for technologies that generate negative emissions are still lacking.

How much negative emissions does Germany need?

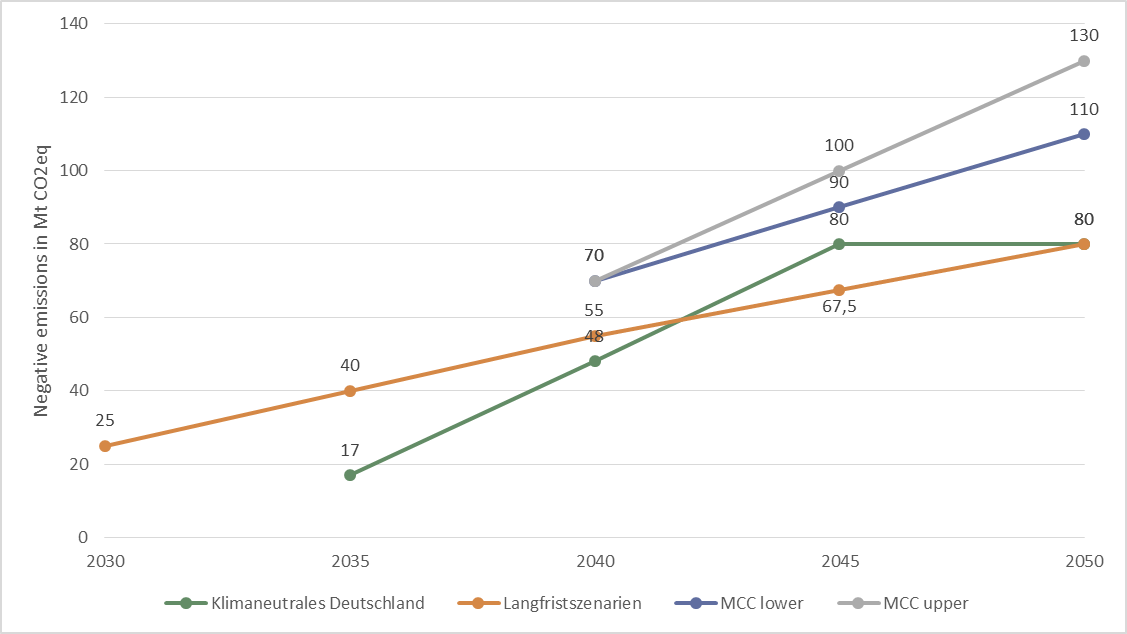
In this analysis we present and compare the results and implications of three detailed studies released during the past three months: the study Klimaneutrales Deutschland 2045 (Climate neutral Germany 2045) by Agora Energiewende, the outcomes of the Fraunhofer ISI project Langfristszenarien für die Transformation des Energiesystems in Deutschland (Long-term scenarios for the transformation of the energy system in Germany) commissioned by the German Ministry for Economic Affairs and the working paper Wissensstand zu CO2-Entnahmen (Knowledge base on CO2-removals) by the Mercator Research Institute on Global Commons and Climate Change (MCC). 

Based on those three publications, figure 2 depicts the projected needs for negative emissions in Germany. All of the studies agree that negative emissions in the order of several ten to hundred millions of tons CO2eq will be needed in Germany by 2050 to achieve the country’s climate targets.

Figure 2: Amount of negative emissions including LULUCF sector needed in Germany from 2030 onwards in Mt CO2eq (missing numbers in studies have been linearly interpolated) (source: cr.hub)

According to current estimates Germany emitted about 740 Mt of greenhouse gases in 2020. As figure 2 shows, the negative emissions necessary by the time Germany wants to reach climate neutrality (2045) range from 67 to 100 Mt CO2eq, so 9 to 13 per cent of 2020’s emissions. Scaling-up nature-based and technological solutions and technologies is already required starting today and in this decade. At present, the use of technologies to remove CO2 from the atmosphere is comparatively expensive. Reducing these costs requires massive investments in technical and organisational infrastructure, and comprehensive political and economic support.

To some extent the new German climate law takes into account negative emissions and aims at a contribution of LULUCF sector of 25, 35 and 40 Mt in 2030, 2040 and 2045, respectively. However, land-use and forestry related carbon removal suffer from low permanence, tricky accounting and potential reversibility through misaligned management practices or natural events such as wildfires.

Thus, in addition to negative emission from the LULUCF sector as part of nature-based carbon removal solutions, technological removals will be needed as well according to all of the three studies. In a coming article we will dive deeper into the proposed kinds of negative emissions solutions for achieving Germany’s climate targets and the potential of some of those solutions. 

To learn more about carbon removal and how it can play a role for your company’s climate strategy, follow us on Twitter or LinkedIn, subscribe to our newsletter or directly get in touch with us.

How much carbon do we need to take out of the atmosphere? Current global scenarios

Net zero targets are taking centre stage in climate policy and action. Depending on the speed of emissions reductions in the coming years and the ambition level of climate goals, negative emissions and thus carbon removal from the atmosphere will be instrumental for achieving those targets. To get a better picture of the scale required we dig into the latest global reports on Net Zero scenarios. 

Net Zero terminology

Even after aggressive emission reduction have taken place, residual emissions might still occur. Greenhouse gases must then be actively removed from the atmosphere in order to further reduce emissions on balance. A country or organisation achieves net zero emissions or climate neutrality when the amount of emissions removed reaches that of the residual emissions, i.e. when no more greenhouse gases are released into the atmosphere on balance. Emissions removed from the atmosphere are also called negative emissions. Various negative emissions technologies exist, which today mainly focus on the removal of CO2 as the most important greenhouse gas from the atmosphere, hence the focus on carbon removal.

Here it is necessary to differentiate between carbon removal, carbon capture and storage (CCS) and carbon capture and use or utilisation (CCU). CCS prevents emission from fossil fuels from entering the atmosphere in the first place, but does not remove any emissions from the atmosphere. In that respect it is not a negative emissions technology or solution. CCU refers to the use of captured CO2 in the production of fuels or other products. If a particular CCU process and product actually leads to negative emissions or not depends on where the captured CO2 comes from and on the life-time of the product in question. Figure 1 explains the difference between carbon removal, CCU and CCS.

Figure 1: Differences between Carbon Removal, CCU and CCS (source: cr.hub)

Clearly, terminology is important when it comes to setting and specifically achieving credible Net Zero targets or climate strategies as well as when evaluating Net Zero claims or scenarios.

Assessing global scenarios

Given the vast amount of global climate scenarios and modeling exercises we only focus on a few of them in the following. Figure 2 shows an exemplary emission pathway for achieving 1.5°C, while at the same time showing traditional mitigation technologies, such as renewables and energy efficiency and carbon removal separately. The figure is based on data from the Network for Greening the Financial System (NGFS) climate scenarios for central banks and supervisory authorities.

Figure 2: Necessary order of magnitude for carbon removal for emission paths of 1.5 °C (source: cr.hub)

In order to widen the scope of the analysis and to reduce the risk of looking in only one direction, we included scenarios of five different organisations:

The International Energy Agency’s (IEA) Net Zero by 2050 Roadmap, the Consultation Paper Reaching climate objectives: the role of carbon dioxide removals by the Energy Transitions Commission (ETC), the Special report: Global warming of 1.5°C of the Intergovernmental Panel on Climate Change (IPCC), McKinsey’s Climate math: What a 1.5-degree pathway would take and NGFS’s Climate scenarios. A few numbers on the relevant amount of negative emissions has been distilled from the report The case for Negative Emissions by the Coalition for Negative Emissions. We are aware that this selection only captures part of the available literature.

All scenarios considered aim to keep the temperature increase below 1.5 °C compared to pre-industrial levels. Still, comparing scenarios and studies is difficult due to different assumptions on which part of the economy and thus which emissions are included in the scenario or what exactly qualifies as carbon removal and what does not. In addition, the probabilities in keeping below a certain temperature threshold differ between scenarios and studies.

All of the above shows that increasing attention needs to be paid to making modeling and scenario assumptions for Net Zero as clear as possible in order to understand the implications of the scenario outcomes. 

Rapid scale-up of carbon removal needed

What do the scenarios have in common?

Emission reductions from large-scale deployment of renewables and electrification of large parts of the industrial and transport sectors are included in all scenarios. Yet, all scenarios agree that there is a significant need for negative emissions in the gigatonnes (Gt CO2eq) range to achieve the 1.5°C climate target, as Figure 3 shows (data sources: Coalition for Negative Emissions, IEA).

Also, carbon removal technologies have to be available on a large-scale basis already during this decade and reach the Gt level by about 2030 from a very low level today. Given today’s greenhouse gas emissions of almost 50 Gt per year, the removals needed according to the five scenarios in 2050 amount to about 5 to 20 per cent of current global emissions. This is a stark reminder that negative emission technologies are not marginal implementations and potential fixes on the race to Net Zero, but important requirements to deal with residual emissions in laggard and hard-to-abate sectors.

Where do the numbers disagree and why?

On the upper end are the high range numbers of the ETC and the IPCC with up to 10 GtCO2eq of carbon removal by mid-century, while the IEA’s Net Zero Roadmap features on the lower end with an expected need of 2.4 Gt of negative emissions by 2050. The IEA foresees a total capture of 7.6 Gt including CCS and CCU. However, removals from the atmosphere make up only about 30 per cent of those. Also, the scenario assumption of the IEA include no new investments into unabated coal power plants and new oil and gas fields or coal mines from 2021 onwards, as well as the phase-out of unabated coal power globally by 2030. The level of ambition for classical mitigation strategies is very high here compared to the other four scenarios.

Figure 3: Required negative emissions for 1.5°C climate targets according to different scenarios in Gt CO2eq/year (source: cr.hub)

If a medium pathway such as in the NGFS or McKinsey scenarios is taken seriously, that means that negative emission technologies (NETs) need to be scaled up rapidly within the coming decades to achieve a removal potential in the Gt scale. A scale-up of at least 50 times from the present days is needed for that according to The case for Negative Emissions report. Especially as the current pipeline for carbon removal projects including Natural Climate Solutions, Bioenergy with CCS and Direct-Air-Capture until 2025 only stands at about 0.15 Gt (source: Coalition for Negative Emissions).

Implications for policy

To achieve net zero by 2050 while keeping global temperature below 1.5°C will require unprecedented efforts and are seemingly not plausible any longer without large-scale utilisation of carbon removal. Indeed, even many 2-degree pathways hinge on negative emissions although on a lower level, especially if international climate action falls short of more ambitious action (source: Minx, et. al., Fuss et. al.).

This leaves policy makers with many questions, such as:

  • Which ways exist to integrate carbon removal in climate policy?
  • What is the interaction between emission reduction and removal policy?
  • How to scale-up NETs and innovation in the sector?
  • Where to focus investments and resources?
  • How to implement carbon removal credits and how to integrate them into the emission trading systems such as the EU ETS?

On the EU-level the first initiatives are on their way to support carbon removal, such as the Negative Emissions Platform and the European Commission wants to propose a robust carbon removal certification system by 2023. In addition, research and innovation on carbon removal are being funded by Horizon 2020 and the follow-up program Horizon Europe. The Innovation Fund, which receives 10 billion EUR from the income of the EU Emission Trading System, includes the commercial demonstration of low-carbon technologies, such as carbon removal and CCS into its framework. 

As an example of how increased climate ambition leads to negative emissions is the case of the German new climate law. In a forthcoming article, we will have a closer look at the need for carbon removal in Germany’s road to greenhouse gas neutrality.

How is the industry preparing?

For the private sector, especially for corporations and companies that set climate targets and aim to go for their own net zero goals, the complexity of the discussion rises. Internationally acknowledged standards of setting climate targets and the role removals and reduction play within those such as the Net Zero Standard by the Science Based Targets initiative will be of great importance (source: SBTi).

Industry-led initiatives on voluntary carbon markets such as the Taskforce for Scaling Voluntary Carbon Markets (TSVCM), where cr.hub is part of the consultation group are needed as well to drive the demand and market. The TSVCM just launched their report of Phase II of implementing an industry-wide carbon market. However it is important that only high-quality removals feature in those industry-led initiatives in order to achieve real climate benefits. The discussion of what a high-quality removal actually entails, is a story for another time. We will come back to that in further articles.

In conclusion it becomes clear thatmany players and organisations are taking carbon removal and negative emissions now much more seriously in their climate and energy modelling scenarios and as a potential tool for reaching net zero targets. In addition, NETs have to be scaled dramatically in order to achieve the required removal potential.

Get in touch with us to learn more or subscribe to our newsletter.

Carbon. Removal. Accelerated.

With this motto, our goal is to counter climate change also with carbon removal and negative emissions. carboneer guides your company through carbon markets, negative emissions and climate strategies.

But first things first: 

What is Carbon Removal and how does taking CO2-emissions out of the atmosphere relate to global climate goals?

CO2-emissions back at pre-Corona levels

Looking back at the past year, the Corona pandemic will probably be the most remembered thing of 2020. And in the public perception, the pandemic and its effects seem to have displaced climate change as the biggest challenge.

As a result, global energy-related CO2-emissions also fell by about 6 percent in 2020 compared to 2019. Due in particular to lockdown restrictions and the economic crisis, energy-related emissions fell by more than 2 gigatons in 2020 to just over 30 gigatons. No one expected such a drop in emissions in early 2020. In fact, some countries, such as Germany only achieved their climate targets as a result of the Corona crisis. Otherwise emissions would not have dropped that much. 

However, a look at the latest figures and statistics reveals that energy-related CO2-emissions have been back at the previous year’s level since December 2020 and could end up just 1 % below pre-Corona emissions of 2019 during 2021. 

Carbon Removal essential for climate goals

Let’s leave 2020 and 2021 behind for a moment and look at how CO2-emissions would have to develop to meet the Paris Climate Agreement’s 1.5 or 2 degree target. For that to happen, carbon emissions would have to decline globally by about the same factor (3-7 percent) each year for the next few decades as they did during the Corona pandemic.   

However, based on the most current plans of the various countries regarding their climate targets (Nationally Determined Contributions), it is more likely that the overall decrease in emissions will be no more than 2 percent by 2030 compared to today. This corresponds to a temperature increase of 2.4 ˚C from pre-industrial levels. Because of these realities, the discussion about large-scale atmospheric removal of CO2 through negative emission technologies is gaining momentum. 

Necessary order of magnitude for carbon removal for an emission path of 2 °C (Data source: NGFS (Network for Greening the Financial System) Scenario Explorer. Model: REMIND-MAgPIE 1.7-3.0; provided by IIASA)

Carbon Removal solutions need support

All solutions are needed in the fight against climate change, from emission savings and reductions to the removal of greenhouse gases from the atmosphere. For a process or technology to be considered carbon removal, four conditions must be met:

  1. CO2 is physically removed from the atmosphere.
  2. the removed CO2 is permanently stored outside the atmosphere.
  3. emissions generated during the process are included in the overall balance.
  4. emissions generated during the process are less than the negative emissions produced.

However, scaling and application of the various nature-based and technological solutions to remove carbon dioxide from the atmosphere are still in their infancy.

Selected negative emission technologies

Based on scientific research from the IPCC reports, these negative emission technologies will need to remove and permanently store several gigatons of CO2 per year from the atmosphere over the coming years and decades. This is roughly equivalent in magnitude to the decline in CO2-emissions caused by the Corona pandemic, the largest economic collapse since the 1930s. 


carboneer: the experts on CO2 markets and negative emissions

Against this background, Simon Göß and Hendrik Schuldt founded carboneer.

Our expertise covers mandatory carbon markets and negative emissions. Through our consulting services (link) we help companies to understand the complexity of carbon markets, to meet the legal requirements and to successfully use negative emissions for the company’s climate strategy. 

Feel free to contact us with your questions.

Let’s take the next step towards solving the climate crisis together.

Your team from carboneer.